What is the scope and industry significance of the Measurement While Drilling Market?
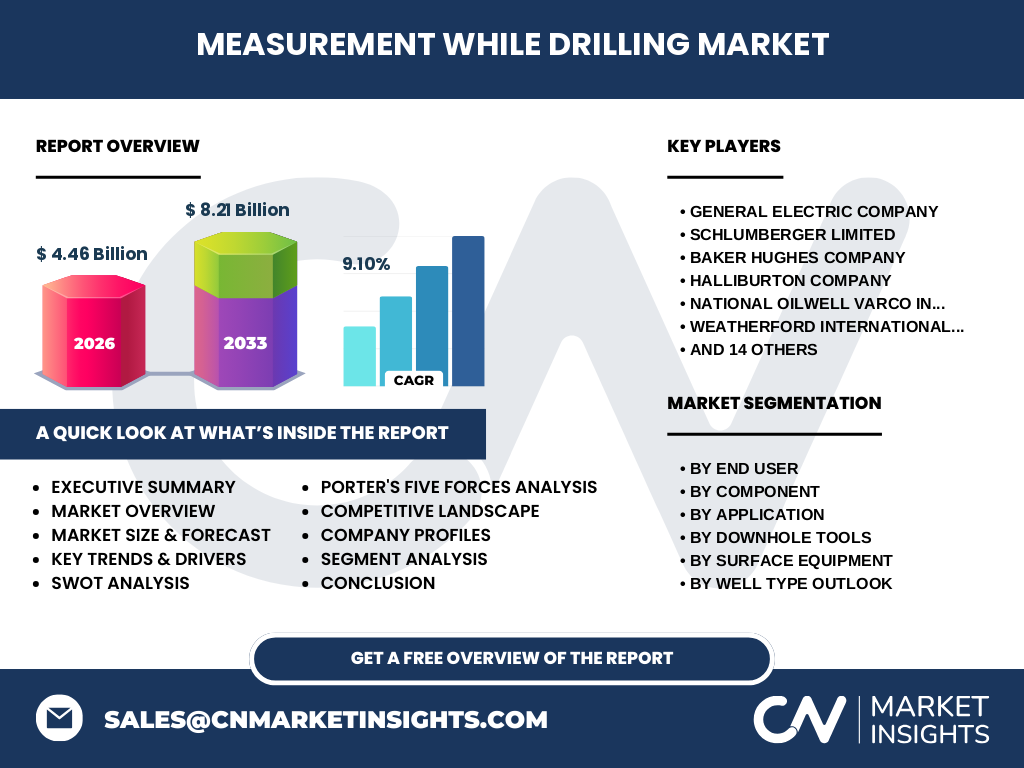
Our analysis indicates that the Measurement While Drilling Market commands a valuation of $4.46 Billion in 2026. This sector encompasses critical downhole tools, sensors, and telemetry systems essential for modern hydrocarbon extraction and geothermal energy exploration, driving precision in complex wellbore trajectory management.
Structural Growth Drivers and Market Restraints
The market is propelled by surging demand for complex horizontal and directional drilling operations. Key restraints include high capital expenditure requirements for advanced pulse telemetry tools and stringent environmental compliance mandated by bodies like the EPA, which restrict rapid deployment in sensitive onshore basins.
Emerging Trends and Growth Patterns in the Sector
Industry trends highlight an aggressive pivot toward software-enhanced solutions and multi-phase measurement systems. Predictive analytics software and high-temperature-resistant gamma ray sensors are gaining rapid traction, allowing operators to optimize drilling parameters in real time across ultra-deepwater environments.
How did COVID-19 impact the Measurement While Drilling Market and recovery trajectory?
The pandemic triggered severe supply chain disruptions and a collapse in rig counts globally. However, the recovery trajectory has been robust, fueled by energy security imperatives that accelerated digital transformation and automated rig site operations among tier-one service providers.
Competitive Benchmarking and Market Concentration
Market concentration remains moderately high, dominated by oilfield services giants like Schlumberger Limited, Baker Hughes Company, and Halliburton Company. These industry leaders leverage proprietary rotary steerable systems and extensive global logistics networks to outpace regional service providers.
Executive Summary: High-Level Synthesis of Key Findings
Our research projects the Measurement While Drilling Market to expand from $4.46 Billion in 2026 to reach $8.21 Billion by 2033, registering a strong CAGR of 9.10%. Growth is heavily concentrated in technologically advanced directional drilling projects across offshore and unconventional plays.
Measurement While Drilling Market Forecast (2027 to 2033)
The forecast period witnesses accelerated adoption of hybrid power units and turbine generators. Driven by a 9.10% CAGR, the market will scale to $8.21 Billion by 2033, as operators prioritize real-time data processing to minimize non-productive time in deepwater basins.
Segmentation Analysis: Core Categories and Market Roles
The market segments into end users, components, applications, downhole tools, surface equipment, well types, technologies, power supplies, data software, and sensors. Oil and gas companies represent the primary revenue source, relying on downhole tools like drill collars and stabilizers to execute precise trajectories.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America leading due to extensive shale play development. Meanwhile, offshore basins in the Middle East and Asia-Pacific exhibit accelerated demand for advanced electromagnetic and mud-pulse telemetry systems to support complex offshore production.
In-Depth Regional Review of Key Markets
North America dominates through intense activity in unconventional tight oil plays, whereas the Middle East focuses on massive offshore developments managed by national oil companies. European markets emphasize stringent regulatory compliance, favoring greenfield technologies with lower carbon footprints.
Strategic Positioning of Leading Companies
Industry titans such as Weatherford International plc and National Oilwell Varco Inc. focus on integrated digital ecosystems. Meanwhile, niche innovators like Scientific Drilling International and Enteq Technologies plc carve out defensible moats through specialized directional drilling and rotary steerable technologies.
Porter's Five Forces Analysis of the Industry
Bargaining power of buyers is moderate due to high switching costs associated with proprietary downhole telemetry software. Threat of substitutes remains low because real-time directional data is irreplaceable for complex wellbore placement, though rivalry among top-tier service providers is intense.
SWOT Analysis of the Measurement While Drilling Landscape
Key strengths include high proprietary technology barriers. Weaknesses involve vulnerability to commodity price volatility. Opportunities lie in automated software integration, while threats stem from accelerated global energy transition policies and regulatory headwinds.
Value Chain Analysis: From Raw Materials to End-Users
The value chain initiates with raw specialty alloy sourcing for drill collars, advancing through precision sensor manufacturing and surface equipment assembly, culminating in deployment by energy companies at well sites managed via specialized logistics through major ports and supply hubs.
Investment Insights and High-Potential Areas
High-potential investment areas center around real-time data processing software and hybrid power units. Venture and private equity capital should target firms developing software-enhanced MWD solutions capable of significantly reducing rig-site downtime and operational emissions.
Conclusion and Strategic Takeaways
The Measurement While Drilling Market represents a vital, high-growth segment of the energy technology sector. Reaching $8.21 Billion by 2033, success will heavily favor enterprises that seamlessly integrate hardware reliability with advanced predictive analytics software.
Research Methodology for Baseline Estimation
Our baseline estimates are triangulated by combining exhaustive trade registry data, primary stakeholder interviews with drilling engineers and c-suite executives, and secondary macroeconomic indicators from international energy agencies to ensure maximum market accuracy.
Scope of the Report and Coverage Parameters
This report evaluates the global Measurement While Drilling Market across multiple segments, forecasting revenues from 2027 to 2033. Limitations include unpredictable geopolitical shifts impacting regional rig counts and sudden regulatory policy alterations across key jurisdictions.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum features strategic mergers, technological partnerships for automated drilling, and product launches targeting low-emission operations. Companies like Hunting PLC and Jindal Drilling And Industries Ltd. continue expanding their technological portfolios to capture emerging offshore opportunities.